There is a useful distinction buried in how AI is being sold to finance teams, and almost nobody draws it.
Nearly every tool on the market is a task agent. It is organised by function — a thing that codes transactions, a thing that prepares a GST return, a thing that drafts a variance commentary. You give it a bounded job, it does the job, it hands you the output, and it forgets you. It is genuinely useful and it is genuinely fast, and it has made the individual legs of finance work cheaper than they have ever been.
The second kind barely exists yet. A journey agent is organised not by function but by client and by period. It is assigned to one business for one financial year with a single objective, it holds everything it has ever learned about that business, it wakes itself up when a date or an event demands it, and it does not hand over to anybody. The venture firm a16z, writing about this pattern in October 2026, called it winning the relay race, and used plaintiff law as the example: a case agent assigned at intake that drives the matter to settlement without a baton ever being dropped.
The framing transfers to accounting almost without translation. It is worth taking seriously, and it is worth being clear-eyed about what is actually hard.
The relay race
Think about what happens to a single client across one financial year in a typical practice.
Someone onboards them. The client transacts for twelve months. A bookkeeper codes and reconciles, usually monthly, sometimes not. An accountant picks the file up at year end and prepares the workpapers. A manager reviews, then a partner reviews. A tax agent files, and — if there is time — somebody has an advisory conversation about what the numbers mean.
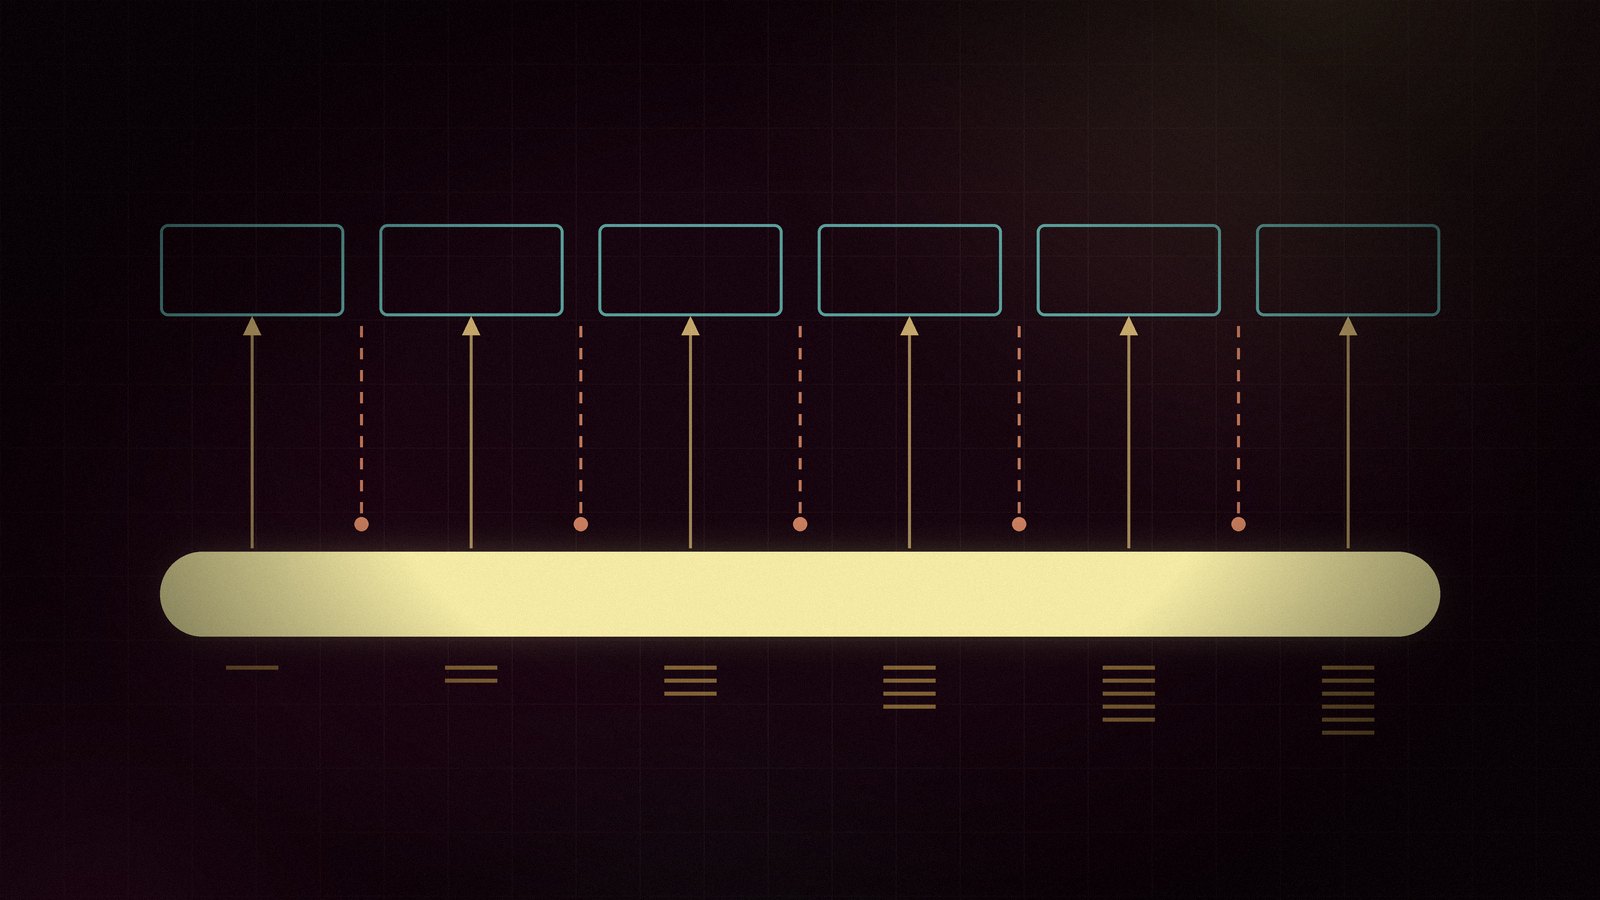
Six legs. Four or five people. Twelve months. And between every pair of legs there is a handoff, which is to say a moment where context is written down incompletely, or not at all, and the next runner starts from a worse position than the last one finished in.
Each individual leg is already done competently. The bookkeeper codes well. The accountant prepares well. The partner reviews well. Nobody in this picture is bad at their job.
The losses are not inside the legs. They are in the gaps — and no amount of making each leg faster closes a gap.
Where your year actually leaks
Five leaks recur, in our experience, across almost every practice and almost every in-house team of any size. They are not exotic. You will recognise all of them.
| The gap | What leaks | Why it happens |
|---|---|---|
| Onboarding to transacting | The query that was raised and never chased | Nobody owns an open question across a twelve-month boundary. It sits in a sent-items folder. |
| Transacting to coding | Context lost at handoff | The person who knew why that payment was unusual is not the person coding it four months later. |
| Coding to year-end | The job that gets under-worked | Capacity is finite, so a small client gets the quick version. Nobody decides this; the calendar decides it. |
| Year-end to review | Deadlines seen too late | The file arrives at the reviewer with no slack left, so review becomes a check rather than a challenge. |
| Review to filing and advice | Last year's answer asked again | The election taken, the position held, the reason for it — recorded in a file note nobody reads, or in somebody's head. |
Price any one of these and it looks small. Price them across a portfolio of two hundred clients across four years and they are the difference between a practice that scales and a practice that just gets busier.
The fifth one is the expensive one. A business that has to re-explain its own structure to its own accountants every year is paying for the same work repeatedly, and knows it. It is also the leak that makes clients leave, because it is the one they can see.
An agent organised by journey
Now put a single agent on that client for the whole year.
It is assigned at onboarding with one objective: a correct, complete, filed year with no surprises. It does not sleep between engagements. It wakes on the GST cycle, on provisional tax dates, on the balance date, on a bank feed arriving, on a covenant test falling due. It dispatches the specialist agents — ledger, compliance, close, reporting, forecast, capital, governance — to do the bounded work they are good at, then consolidates what comes back. It writes everything to a case file it can read again in eleven months. And when something crosses a materiality threshold, it escalates to a Chartered Accountant, who judges it, overrides it where necessary, and signs.
The legs do not change. The specialists do the same bounded tasks they did before, no better and no worse. What changes is that there is now something underneath all six legs that never hands over.
A task agent makes each leg faster. A journey agent removes the gaps. Only one of those changes the economics.
What it is made of
Described loosely this sounds like magic. Described properly it is six components, four of which already exist in any serious AI finance platform.
- Wake sources. The agent is not prompted by a person. It is woken by the compliance calendar, by a bank feed, by a threshold being crossed. This is the part that makes it long-running rather than merely long-lived.
- The case file. Durable, structured memory of one client: every query and its answer, every election taken, every position held, who judged what and when. Not a chat history — a record designed to be read by a machine next year.
- Dispatch. The journey agent does not do the work. It decides what work is needed, sends it to the specialist built for it, and assembles the results.
- Deterministic execution. Every number is produced by code, not by a model. The model reasons about what to calculate; arithmetic is done by something that cannot be creative. This is non-negotiable and it is where most demos quietly cheat.
- The immutable log. Written once, never amended. If an auditor or Inland Revenue asks why a position was taken in March, the answer exists and has not been rewritten since.
- The escalation gate. A materiality threshold above which a human sees it. The agent's most important judgement is not the accounting — it is deciding what a person must look at.
Notice what is not in that list: autonomy over filing, authority to correspond with a revenue authority, or discretion over a judgement call. None of those belong to a machine, and a design that assumes they do is not a bold product decision. It is an unallocated liability.
The arithmetic that constrains it
Here is the constraint that decides whether any of this is buildable, and it is arithmetic rather than opinion.
A compliance year, decomposed into the discrete steps an agent actually has to get right, runs to roughly fifty of them. If each step is 99% reliable, the probability that the whole journey completes correctly end to end is 0.9950 — about 60%. Lift every step to 99.5% and it is 78%. Those are not acceptable numbers for work that carries a signature.
You cannot engineer your way to a fifty-step chain that completes reliably. What you can do is break the chain — put verification gates at the points where an error would otherwise compound, so that a mistake at step nine is caught at step ten instead of being inherited by steps eleven through fifty.
This is why a serious journey agent is checkpointed at the signature rather than running autonomously to the end. The limit is not ambition. It is multiplication.
Anyone selling fully autonomous end-to-end finance should be asked for their per-step reliability figure and their step count, and then asked to multiply. The answer is usually the end of the conversation.
What it does to fees
The commercial argument in the a16z piece is that owning a whole journey lets a vendor price on the outcome rather than on the hours saved, because the outcome is observable and attributable. In plaintiff law the outcome is a settlement figure. The analogy to accounting is tempting and needs care.
Tax saved is the obvious candidate and it is the wrong one. A fee calculated as a share of tax saved creates a direct self-interest in the aggressiveness of a position, which is a textbook threat to objectivity, and the professional standards question is not a close call. We treat it as off the table.
The defensible version is quieter and, in our view, better. Hold a value-based fee while the cost of producing the work collapses underneath it. The client gets a materially better service — queries chased, deadlines seen early, the file worked fully rather than to the time available — and the margin on delivering it expands. That is margin expansion, not revenue sharing, and it does not require anybody to take a position on a tax outcome they are paid to influence.
Fee structures, contingent arrangements and the professional-standards position on each are matters to confirm with CA ANZ and your own professional-standards adviser before you build or sell on them. Nothing here is legal, tax or professional-standards advice.
Where it breaks
Four honest failure modes, all of which we think about constantly.
- Error compounding, covered above. It is the binding engineering constraint and no architecture removes it — the best you can do is contain it.
- Accountability. If an agent runs a client's year and something is wrong, the question is who is accountable. The only answer that survives contact with a professional indemnity insurer is a named Chartered Accountant who reviewed and signed. Any design where the honest answer is "the system" has shifted risk onto a party who cannot carry it.
- Acting outside the firm. An agent that chases a client for information is useful. An agent that corresponds with Inland Revenue is a different category of thing, with a different set of obligations attached, and should not be built casually.
- Data and learning. There is real tension between telling clients their data is never used to train models and designing a system that improves because it has seen their cases. The honest resolution is to be precise: a case file improves that client's service, the system learns patterns and procedures rather than client data, and the distinction is written into the engagement terms rather than implied in a sales call.
What to do first
Not a build. The first step is deliberately cheap, takes a day, and will tell you whether any of this is worth the money.
Take ten client files you closed last year. Re-read each one by hand, and count: how many open queries were never resolved? How many times did someone re-establish context that already existed in writing? How many deadlines were seen inside the last fortnight? How many questions were asked that had been answered the year before?
If the leaks are not there, a journey agent is solving a problem you do not have, and your money belongs in better task agents instead. If they are there — and in every portfolio we have looked at, they are — you now have a number, and the business case writes itself rather than being asserted.
Make each leg faster and you get the same race, run quicker. Remove the handoffs and you get a different race.
XLCFOWe run supervised finance agents behind a Chartered Accountant review gate, with a durable case file per client and deterministic execution on every number. Nothing reaches a board, a lender or a regulator without a named human signature.
The relay-race framing and the three go-to-market routes referenced here are from “Winning the Relay Race: Long-Running Agents in High-Value Customer Journeys” by David Haber, published by a16z on 14 October 2026. It is a venture firm's thesis piece and we have treated it as framing rather than evidence. The mapping onto a compliance year, the five leaks, the architecture and the reliability arithmetic are ours.